Insurance companies depend on accurate customer data to assess risk, issue policies, manage accounts, and handle claims. But collecting that information can be difficult when customers have to provide it through paper forms, PDFs, email, phone calls, and disconnected digital channels. A digital customer journey can bring these interactions together and make customer data collection easier to manage.
The challenge is not simply collecting more data. Insurers need to collect the right information accurately, keep it up to date, and make it easy for customers to provide. In this guide, we'll look at eight common types of customer data in insurance and practical tips for collecting each one. For a deeper look at the topic, see our guide to customer data intake in insurance and our overview of digital insurance workflows.
What is customer data in insurance?
Customer data in insurance is information an insurer collects about its customers and their policies. It can include basic personal details, policy information, claims history, payment information, interactions with the insurer, signatures, agent information, and supporting documents.
The type of information collected depends on the insurance product and the customer's relationship with the insurer. An application, for example, requires different information from a claim or a policy update.
1. Personal information.
Personal information is usually collected when a customer applies for insurance and is used to identify and communicate with them.
This can include:
- Name
- Address
- Phone number
- Email address
- Date of birth
- Identification information
- Employment information
- Financial information, where relevant
- Health information, where relevant
The specific information required varies by insurance product. For example, an insurer may need information about a customer's income or health when assessing certain types of coverage, while other policies require much less personal information.
Tip for collecting personal information: Make the process easy to complete and avoid asking customers to enter information the insurer already has. Where appropriate, existing information can be prefilled so customers only need to confirm or update it.
2. Policy information
Policy information contains the details of a customer's insurance coverage.
It can include:
- Policy number
- Type of coverage
- Effective date
- Expiration date
- Coverage limits
- Deductibles
- Covered property or vehicles
- Beneficiary information
- Policy status
Policy information is important for managing policies, handling changes, and preparing for renewals.
For example, an insurer may already know a customer's policy number, coverage type, and address when the customer requests a policy change. Asking the customer to enter all of that information again creates unnecessary work.
Tip for collecting policy information: Use existing policy data whenever possible and ask customers to confirm what is still accurate rather than recreating the entire policy record.
3. Claims history
Claims history records previous claims associated with a customer or policy.
It can include:
- Date of the claim
- Type of claim
- Description of the incident
- Claim status
- Claim outcome
- Amount paid
- Supporting information
Claims history can help insurers understand a customer's previous experience and assess risk.
The information collected during a new claim can also become part of the customer's claims history. This may include information about the incident, the people involved, the damage, and supporting evidence.
Tip for collecting claims information: Use clear, straightforward questions and allow customers to provide supporting information such as photos and documents as part of the same submission.
4. Payment history
Payment history records financial transactions associated with an insurance policy.
It can include:
- Payment dates
- Payment amounts
- Payment status
- Payment method
- Billing information
- Outstanding balances
- Refunds
Payment information helps insurers manage billing and provides customer service teams with visibility into an account.
Tip for collecting payment information: Keep payment-related questions focused on what is actually needed and make it clear to customers what information they need to provide.

5. Interaction history
Interaction history records a customer's previous communications and interactions with the insurer.
This can include:
- Phone calls
- Emails
- Chat conversations
- Service requests
- Previous submissions
- Portal activity
- Communication preferences
Interaction history gives insurers a record of the customer's relationship with the company and can help employees understand previous requests or issues.
It can also help identify where customers repeatedly need assistance.
For example, if customers regularly contact an insurer after submitting a request because they are unsure whether it was received, that interaction data can reveal a gap in the customer experience.
Tip for collecting interaction data: Keep customer interactions connected wherever possible so employees can see relevant information without asking customers to repeat their history.
6. Signatures
Insurance transactions can require customers to sign documents or confirm information.
Signatures may be needed for:
- Applications
- Policy documents
- Policy changes
- Agreements
- Other insurance-related documents
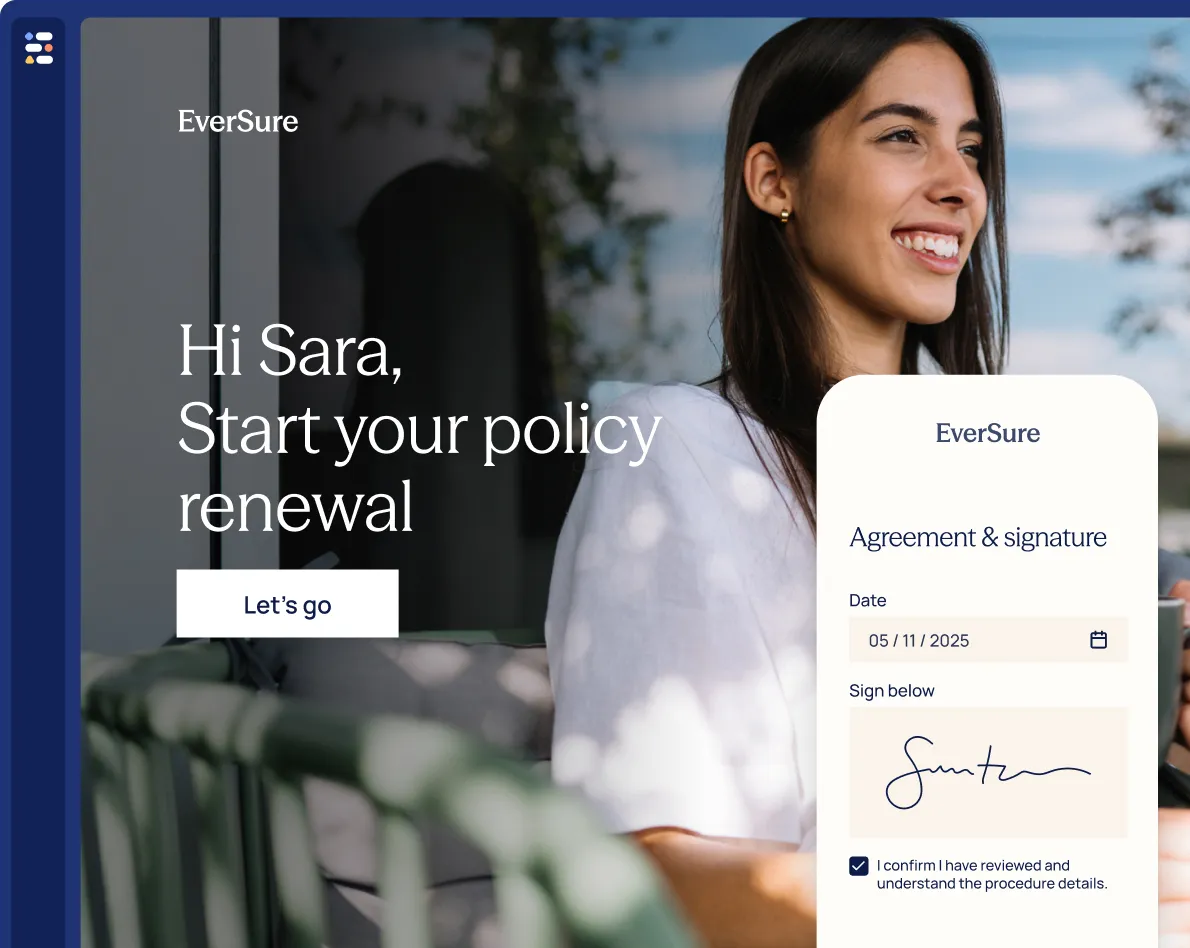
Digital signatures make it possible to collect signatures without requiring customers to print, sign, scan, and return documents.
Tip for collecting signatures: Keep signing within the same digital experience whenever possible. Customers should not have to complete one process, download a document, and start a separate process just to sign it.
7. Agent information
Agent information identifies the agent or broker associated with a customer or policy.
It can include:
- Agent name
- Broker name
- Agency
- Contact information
- Producer information
Keeping agent information accurate helps insurers manage customer relationships and route information to the appropriate people.
Agents can also play an important role in collecting customer information, particularly when they help customers complete applications or other insurance processes.
Tip for collecting agent information: Make it easy to associate customer submissions with the correct agent or broker so information does not have to be matched manually later.
8. Attachments and supporting documents
Customer data is not limited to information entered into form fields. Insurance companies also collect documents, images, and other supporting evidence.
Examples include:
- Identification documents
- Proof of address
- Photos
- Videos
- Receipts
- Repair estimates
- Medical documents, where relevant
- Police reports
- Other supporting records
Attachments are particularly important for claims, where photos, videos, receipts, and reports can provide information that customers cannot communicate through standard form fields alone.
Tip for collecting attachments: Let customers upload documents and images as part of the same digital data collection process instead of requiring them to send attachments separately by email.
Tips for collecting customer data in insurance
Collecting customer data effectively means balancing the information the insurer needs with the effort required from the customer.
Here are seven practical ways to improve the process.
1. Make it easy to provide information
Long, complicated forms can discourage customers from completing a process.
Break complex data collection into clear steps and use straightforward questions. Customers should always understand what information they are being asked to provide.
2. Only ask for information you need
Not every customer needs to provide the same information.
Use the customer's answers to determine which questions are relevant. This keeps the experience shorter and prevents customers from navigating unnecessary fields.
3. Prefill information you already have
If the insurer already has a customer's name, address, policy number, or other relevant information, don't make them type it again.
Prefilling reduces data-entry effort and gives customers a chance to confirm that existing information is still correct.
4. Validate information as customers enter it
Errors are easier to fix at the point of entry than after a submission has reached an employee.
Use validation to identify missing information, incorrect formats, or other problems before the customer submits the data.
5. Make document collection part of the experience
Forms are only one way customers provide information.
When supporting documents are required, include uploads in the same customer experience. This makes it easier for customers to understand what they need to provide and reduces separate email exchanges.
6. Make it easy to update information
Customer information changes over time.
Addresses, phone numbers, employment information, vehicles, beneficiaries, and other details may need to be updated throughout the policy lifecycle.
Customers should have a simple way to update information without having to start from scratch.
7. Connect collected data to the systems that need it
Collecting information digitally is only useful if the data can be used without unnecessary manual work.
A modern data intake process can connect customer information with the CRM or other business systems where employees need it.
This is where digital customer journeys go beyond simple online forms. Instead of ending with a completed submission, the journey can collect information, validate it, capture documents or signatures, and pass the resulting data to the appropriate system.
EasySend's insurance and financial-services materials position digital journeys around this approach: collecting customer data through digital experiences and connecting that information with systems such as Salesforce.
Why digital customer data collection matters
Insurance companies collect a large amount of customer information, but the quality of the collection experience affects the quality of the data they receive.
When customers have to navigate complicated forms, repeat information, or send documents through separate channels, there are more opportunities for incomplete or inaccurate submissions.
A better approach is to make customer data collection:
- Simple for the customer
- Relevant to the specific request
- Easy to complete
- Easy to update
- Connected to the insurer's systems
The objective is not to collect more information. It is to collect better information with less friction.
FAQ

Forget forms. Create digital customer journeys.